Auto parts production is entering a less predictable decade. Electrification, software, and regional sourcing are changing factory decisions. The question “what are the future trends in automotive parts production” now reaches beyond engines and transmissions. It includes battery enclosures, thermal systems, sensors, recycled materials, and secure data links. The International Energy Agency’s Global EV Outlook 2024 reported nearly 14 million electric cars sold worldwide in 2023. They represented about 18% of new car sales. This shift affects supplier tooling, testing, workforce skills, and investment timing.
Industry evidence also shows why trend tracking needs discipline. Deloitte’s 2024 Global Automotive Supplier Study highlights margin pressure, electrification costs, and the need for operational efficiency. McKinsey’s automotive research identifies software-defined vehicles and connected services as important value drivers. These reports are useful, but forecasts are not factory orders. A promising component can fail through high scrap rates, unstable material supply, or unclear customer demand. We have seen dashboards look impressive while one delayed resin shipment stops a production cell. Reality is noisy.
This guide presents seven practical tips for monitoring future movements without chasing every headline. It connects patent activity, OEM sourcing announcements, plant-level trials, energy data, and supplier conversations. Track signals monthly. Compare forecasts with measured yield, lead time, warranty data, and total cost. Keep a written record of what proved wrong. That habit builds experience and protects decisions from fashionable thinking. The goal is not perfect prediction. It is earlier, evidence-based preparation for safer, more resilient, and more competitive parts production.
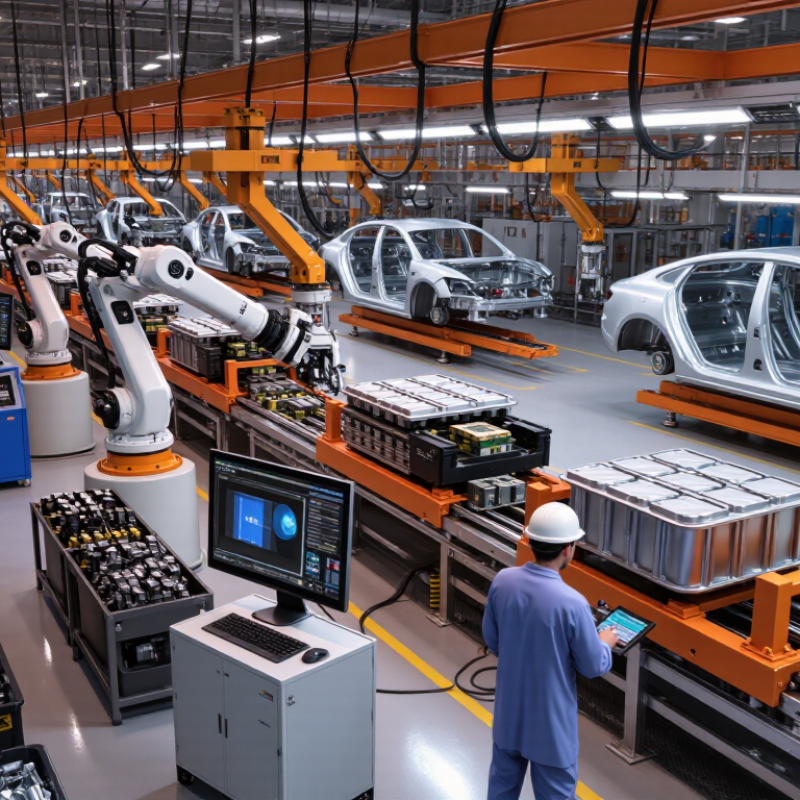
OICA recorded approximately 93.5 million motor vehicles in 2023. This figure gives parts manufacturers a useful production baseline. It also shows the market’s scale before forecasting future demand. Use it as a reference, not a guarantee. Production volumes can change quickly.
Track vehicle output by region, vehicle type, and powertrain. Monitor factory utilization, supplier lead times, material prices, and engineering changes. These signals often reveal demand shifts earlier than annual reports. A simple dashboard can compare monthly orders against the 2023 baseline. Include inventory days and replacement rates. Small changes matter.
Watch the movement toward electrified vehicles, but avoid treating it as a complete forecast. Internal-combustion platforms may remain important in many markets for years. Parts companies should review both technologies. Update tooling plans when customer programs, regulations, or production schedules change. Talk with purchasing teams and production engineers. Their details are often more practical than broad market headlines.
Do not trust one data source. Compare official production statistics with customs data, supplier feedback, and plant-level evidence. I would also test three scenarios: steady growth, weak demand, and rapid technology change. That assumption can fail. Even accurate 2023 figures cannot predict every disruption, especially when models, materials, and regional policies shift. A quarterly review keeps the baseline useful.
Electric vehicle production is no longer a distant scenario.
The IEA’s Global EV Outlook 2025 reports more than 17 million electric cars sold worldwide in 2024. That volume represented about one in five new cars. For auto-parts manufacturers, electrification now requires a practical tracking system, not occasional market watching.
Monitor seven signals each month: battery-cell capacity, charging deployment, inverter demand, thermal-management designs, power-semiconductor orders, recycled-material prices, and regional safety rules.
Watch factory floors closely. A battery-pack line may reveal change earlier than a sales forecast. Fewer engine components can mean stronger demand for cooling plates, high-voltage connectors, sensors, and lightweight structural parts. Small details matter.
The IEA also notes that electric car sales continued growing across major markets in 2024, although regional speed differed sharply. Deloitte’s automotive supplier research highlights software, electrification, and cost pressure as major transformation forces for suppliers.
This means production teams should connect engineering data with purchasing and customer inquiries.
Keep two scenarios: rapid adoption and uneven adoption. Forecasts can be wrong. Mine have been.
Review material contracts quarterly, test alternative alloys, and train workers on high-voltage component handling. A simple dashboard with weekly updates may outperform a complex annual report. Pay attention to failed pilot runs, delayed tooling, and rising scrap rates. They often expose future trends before public statistics do.
Software demand is becoming a practical signal for future auto parts production. The Semiconductor Industry Association reported global chip sales of $627.6 billion in 2024. That figure matters beyond electronics suppliers. It reflects growing demand for sensors, controllers, connectivity, and software-enabled vehicle functions.
Production teams should measure software demand beside physical orders. Track the number of parts requiring embedded code, software validation hours, update frequency, and field-reported software faults. A controller sitting on a warehouse shelf may look complete. It is not production-ready if its code fails testing. Shortage risk can also appear in development tools, memory capacity, or cybersecurity checks.
Electric vehicle growth strengthens this trend. The International Energy Agency reported that global electric car sales exceeded 17 million units in 2024. More electric vehicles usually mean more electronic control and software content per vehicle. However, the relationship is not perfectly linear. Some software features remain unused, and customer adoption can disappoint forecasts. That weakness deserves attention. A useful dashboard should compare planned software functions with actual activation rates, warranty claims, and update requests. Review the numbers monthly, not only during annual planning.
Global semiconductor sales increased from USD 412.3 billion in 2019 to USD 627.6 billion in 2024. This expansion reflects rising demand for electronics, vehicle electrification, connectivity, and advanced manufacturing systems—areas that typically increase the need for production, testing, simulation, and supply-chain software.
Source: Worldwide industry semiconductor sales data, 2019–2024. Values shown in USD billions.
7 Tips to Track Future Trends in Auto Parts Production?
The IEA projects major growth in demand for lithium, nickel, cobalt, graphite, and rare earth elements by 2030. Auto parts manufacturers should treat this forecast as a purchasing risk, not distant market news. A stamped component may look simple, yet its coating, alloy, or electronic sensor can depend on vulnerable minerals. Map every critical material behind each part number. Record the country of mining, refining, and final processing. Track supplier lead times every week. Small delays often appear before price increases.
Use a practical risk dashboard with inventory coverage, geographic concentration, recycled content, and approved alternatives. Ask suppliers whether they can provide material certificates and recent production data. Check incoming samples, because paperwork can become outdated. Build limited safety stock for parts with long qualification cycles. Design engineers should also test lower-mineral or recycled substitutes before shortages become urgent. The IEA outlook supports this approach, but forecasts are not guarantees. A dashboard can still create false confidence. We may overestimate recycling capacity or underestimate transport disruption. Review assumptions quarterly, and challenge suppliers when their answers sound too perfect.
Supplier forecasts can reveal future shifts in auto parts production, but internal data should never stand alone.
Compare monthly demand estimates with OICA production statistics and IEA reports on vehicle electrification, energy use, and technology adoption. This comparison can expose optimistic assumptions before they affect tooling, staffing, or inventory decisions.
Check the definitions.
Supplier data may measure purchase orders, while OICA may report completed vehicles. The IEA may use global scenarios with different regional boundaries and time periods.
Align the calendar, vehicle category, and market before comparing percentages. A practical review can place a supplier’s expected 12% rise beside regional production changes and projected electric vehicle growth.
Large gaps deserve questions, not immediate rejection.
Use a simple evidence sheet.
Record the source date, forecast range, production volume, and confidence level. Track repeated signals across three reporting cycles.
A supplier predicting higher demand for lightweight housings should support that view with confirmed programs, capacity plans, or customer schedules.
My early forecasts were too confident. That mistake mattered. Supplier updates sometimes reflected one delayed project rather than a broad market trend.
Reviewers should also test weak signals, such as falling order frequency, longer payment cycles, or unused production lines.
Data can mislead. Careful comparison creates a more defensible view of future parts demand.
More than 17 million electric cars were sold worldwide. That represented about one in five new cars. Growth varied by region.
Track battery-cell capacity, charging stations, inverter demand, and thermal-management designs. Also monitor semiconductor orders, recycled-material prices, and safety rules.
Factory changes may appear before public sales forecasts. Fewer engine parts can signal higher demand for cooling plates, sensors, connectors, and lightweight structures.
Keep rapid-adoption and uneven-adoption scenarios. Review them regularly. Forecasts can be wrong, including ours.
Review material contracts every quarter. Test alternative alloys and check supplier capacity. Delayed tooling deserves attention.
More vehicles require sensors, controllers, connectivity, and embedded code. A controller is not production-ready until its software passes testing.
Measure coded parts, validation hours, update frequency, and software faults. Compare planned features with activation rates, warranty claims, and update requests.
Often, yes. Weekly updates may reveal rising scrap, failed pilot runs, or delayed tools earlier than annual reports. Still, a tidy dashboard can mislead.
Understanding what are the future trends in automotive parts production requires a structured approach to market data and supply-chain signals. Start with a clear baseline by reviewing the approximately 93.5 million vehicles recorded globally in 2023. Then track electrification through the more than 17 million electric cars sold in 2024, as this shift increases demand for batteries, power electronics, thermal systems, and lightweight components. Software demand is another essential indicator, supported by global semiconductor sales of about $627.6 billion in 2024.
Manufacturers should also audit supply risks by examining the expected growth in demand for key minerals through 2030. This can reveal potential pressure on material availability, costs, and production continuity. Finally, validate internal forecasts by comparing supplier information with reliable international vehicle, energy, and technology reports. Combining production volumes, electrification rates, software growth, mineral requirements, and supplier evidence can help companies identify emerging opportunities and prepare their parts strategies with greater confidence.

Mayumi Auto